 Buying a home with a private well can feel straightforward until you discover that the water source is shared with a neighboring property. Shared wells are common in some rural and semi-rural communities, but they can introduce questions that buyers of homes with municipal water may never encounter. A lender may need to understand not just whether the water works today, but whether the property has a dependable legal right to use it in the future.
A Shared Water Source Creates Shared Responsibilities
When two or more homes rely on the same well, ownership and maintenance responsibilities may be divided among the property owners. One household might have the well equipment on its land while another depends on a pipeline crossing the property line. That arrangement can work well for years, especially when neighbors cooperate. Problems can arise, however, if there is no clear agreement about repairs, electricity costs, access, or what happens when someone sells.
Lenders May Ask for Written Documentation
Depending on the loan program and property circumstances, a lender may request a recorded shared-well agreement or other documentation establishing access and responsibilities. The agreement may address who can use the well, who pays for upkeep, how repairs are approved, and whether each property can continue receiving water if ownership changes. Requirements vary, so buyers should avoid assuming that a handshake arrangement between neighbors will satisfy a lender.
Water Quality and Supply Still Matter
A shared-well agreement does not replace questions about the water itself. A lender, appraiser, or local authority may require information about water quality or whether the system can adequately serve the connected homes. Testing requirements can depend on the loan type, local rules, and property conditions. Buyers may also want to ask about the age of the pump, past interruptions, and whether the system has enough capacity during heavy use.
What to Check Before You Commit
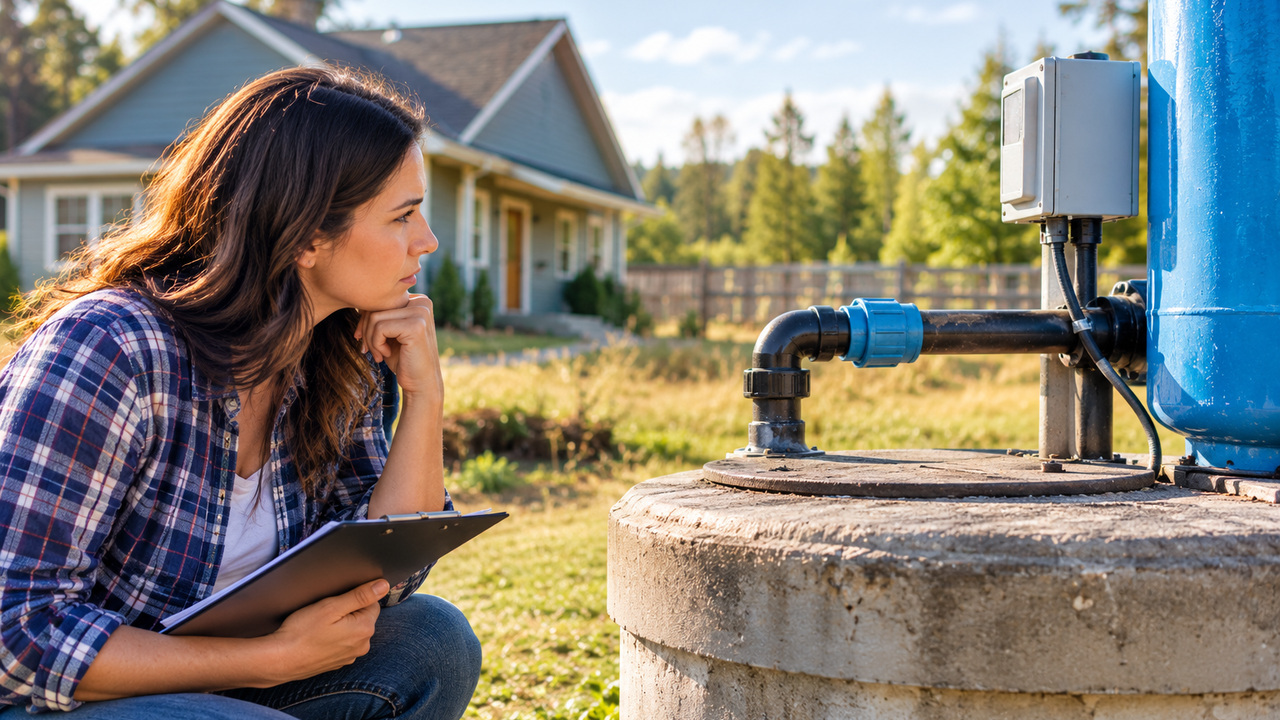
Ask early whether the property uses a private well, a shared well, or a community water system. If it is shared, request copies of existing agreements and find out where the well and water lines are located. Ask who pays the electric bill, whether there is a maintenance fund, and how emergency repairs are handled. A title professional or real estate attorney may help clarify whether necessary access rights are documented.
It is also wise to raise the issue with your lender before the transaction is far along. Discovering a missing agreement shortly before closing can create delays while the parties gather signatures or resolve ownership questions.
A home served by a shared well is not automatically difficult to finance. The key is making sure the water supply is reliable and the arrangement is clear enough for everyone involved. A little investigation early in the buying process can prevent a surprisingly complicated issue from surfacing just as you are preparing to move.